Statutory deductions
How Provident Fund, ESI, professional tax and income tax (TDS) are worked out on each payslip, and how to change every rate, ceiling and slab.
With India payroll rules, four deductions are worked out on every payslip. Every rate is editable under Rules & settings › Pay › Statutory deductions & posting, and any of them can be switched off.
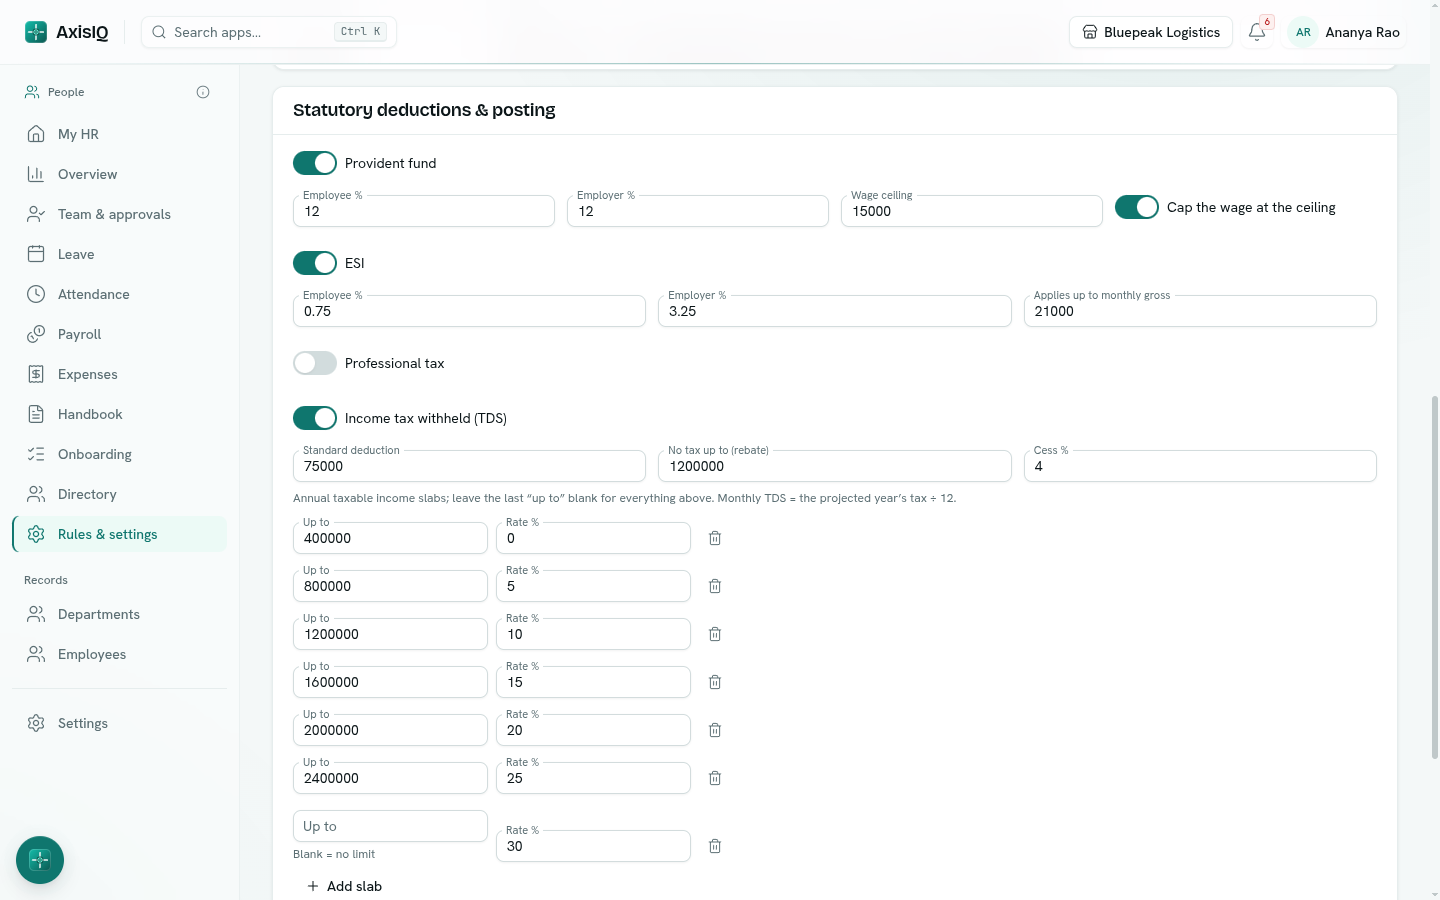
Provident Fund (PF)
| Setting | Starting value |
|---|---|
| Employee % | 12 |
| Employer % | 12 |
| Wage ceiling | 15,000 |
| Cap the wage at the ceiling | On |
Worked out on basic (plus dearness allowance, if you have one) for the month, capped at the ceiling when capping is on, rounded to whole rupees. The employee share is a deduction; the employer share is an employer contribution.
Employees' State Insurance (ESI)
| Setting | Starting value |
|---|---|
| Employee % | 0.75 |
| Employer % | 3.25 |
| Applies up to monthly gross | 21,000 |
Applies when the full monthly gross is at or under the limit. Worked out on the month's gross, rounded up.
Professional tax (PT)
Off to start with, because it differs by state. Turn it on and enter your state's slabs: the monthly gross each slab starts at and the amount.
Income tax (TDS)
| Setting | Starting value |
|---|---|
| Standard deduction | 75,000 |
| No tax up to (rebate) | 12,00,000 |
| Cess % | 4 |
| Slabs | 0% to 4 lakh, 5% to 8 lakh, 10% to 12 lakh, 15% to 16 lakh, 20% to 20 lakh, 25% to 24 lakh, 30% above |
Monthly TDS = the projected year's tax ÷ 12. The year is projected from the month's full taxable pay × 12, less the standard deduction; no tax is due at or under the rebate limit; cess is added on top.
Note: TDS is a projection from the current month. It does not yet take investment declarations or pay already taxed earlier in the year into account. For anyone that matters for, set a fixed monthly TDS on their salary or change it on the payslip.
Other settings
- Salaries are paid on day — printed on payslips.
- Round net pay to whole units.
- Ledger — the expense, payable and statutory dues accounts a finalized run posts to.